Queens flood risk should be checked at the property level using more than one source. Coastal flooding, intense rainfall, drainage problems and sewer backup are different questions. A waterfront view does not establish a property’s exact exposure, and an inland address does not remove the need to investigate.
For buyers in Astoria, Long Island City and the wider borough, the useful approach combines public maps, the property’s history, a physical inspection and insurance advice. This guide provides a due-diligence sequence you can use before committing to a house, condo or co-op.
Queens flood risk: coastal and rainfall checks serve different purposes
NYC HPD’s resiliency resources link to the City’s Flood Hazard Mapper and Stormwater Flood Maps. The first helps explore coastal flood hazards and future conditions. The stormwater maps show modeled rainfall-related flooding under different scenarios. Use both as screening tools, then investigate the particular building.
A map is a starting point for questions, not a building inspection or a guarantee. Save the layer, scenario and date you reviewed so you can explain what you are looking at. A screenshot without its legend can lose the meaning of the information.
Do not label an entire Queens neighborhood safe or unsafe from one property result. Street elevation, building configuration and the location of vulnerable equipment can make the investigation different from one address to another. Keep the discussion tied to verifiable property information.
Start with the exact address and building layout
Confirm the building and unit you are considering. A large development can occupy several lots or entrances, and a marketing address may not answer every record-search question. Ask the listing agent or managing agent to clarify the building identifiers needed for the review.
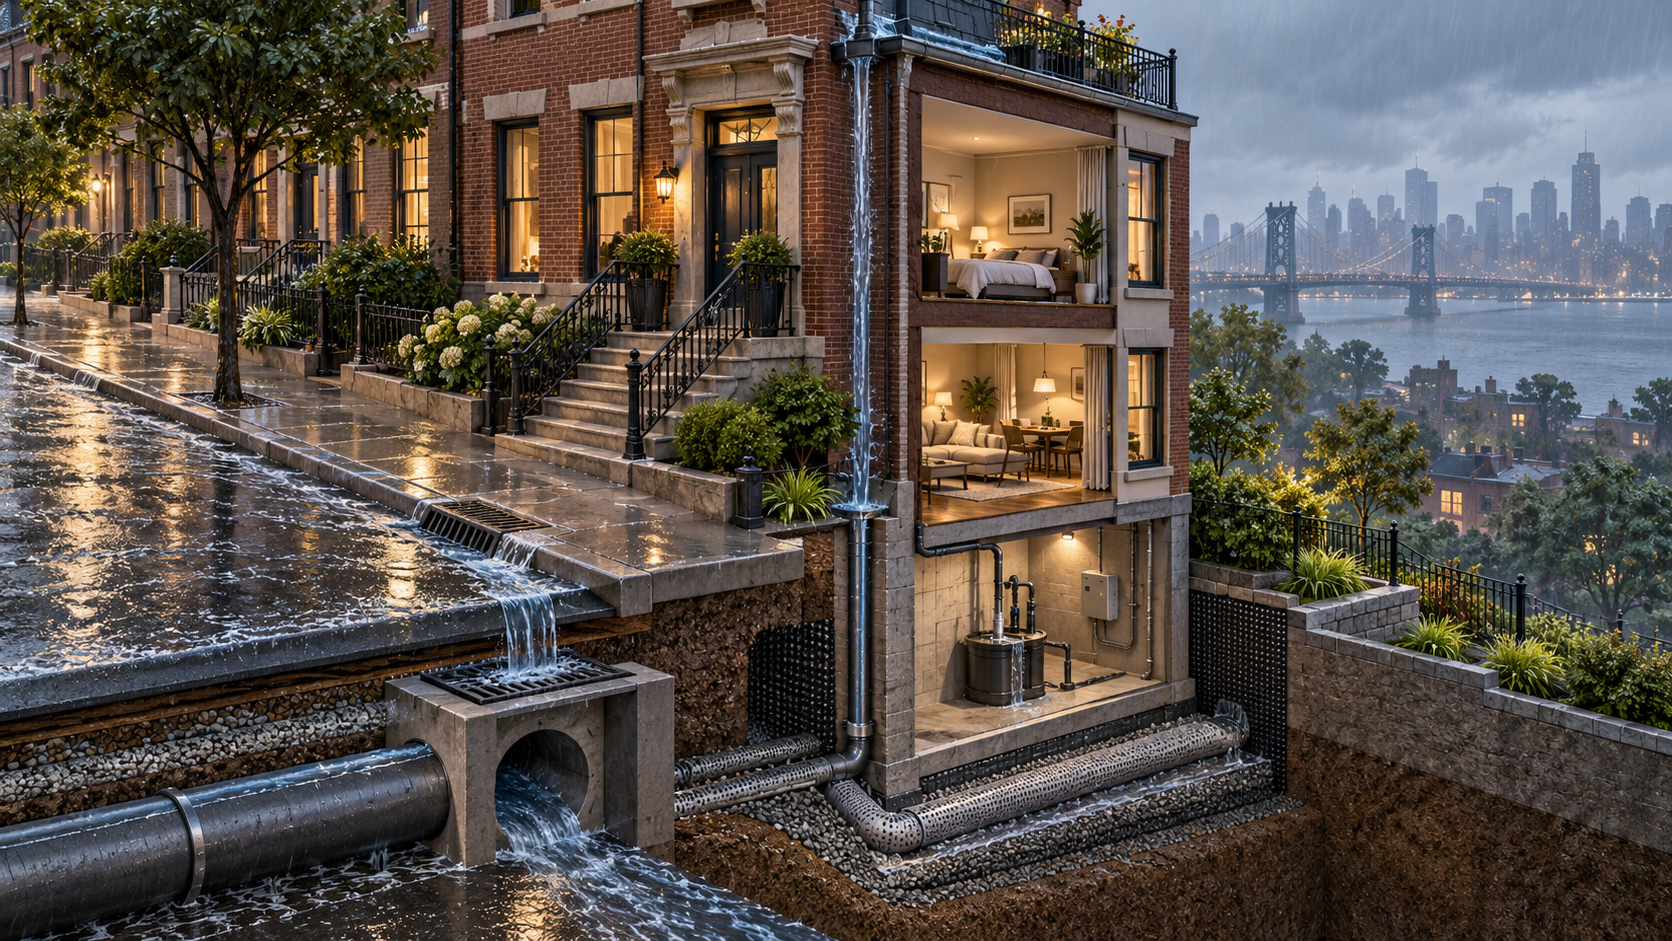
Next, sketch how the space is used. Identify the apartment floor, entrance level, storage location, parking and any lower-level rooms. For a house, note where the boiler, electrical equipment, laundry and other important systems are located. Your inspector can explain what can be evaluated and what needs a specialist.
For an upper-floor apartment, investigate the building as well as the unit. A higher living floor does not answer questions about equipment, access, insurance or the financial consequences of repairs to common areas. Ask who is responsible for each relevant component.
Review maps without treating them as a prediction
Set aside time to examine the property in the official tools. Read the legend, scenario description and limitations. Compare the address with nearby streets and access routes. If a layer appears to affect the block, record the question for the appropriate professional instead of guessing at the implication.
The City’s stormwater dataset describes several scenarios with different rainfall and sea-level assumptions. Those scenarios should not be blended into one claim about how deep water will be in a particular home. Check what the selected layer represents before comparing properties.
A useful note might say: “The address appears near a shaded area in the selected rainfall scenario; ask the inspector and insurer how to investigate.” That is more accurate than writing “this house will flood” or “no risk” based only on the map.
Ask for a documented history of water issues
Request information from the seller about known flooding, water entry, sewer backup and repairs through the appropriate transaction channels. Your attorney can identify the disclosures and records that apply. Keep those answers with the inspection and insurance information for a coordinated review.
If the owner completed repairs, ask which problem the work addressed and when it occurred. Also request available invoices, permits and warranties. A freshly finished lower level does not explain the reason for the work. At the same time, repairs do not establish that a property is unsuitable.
Request specific information rather than a general assurance that everything is fine. Was the issue connected with a roof leak, groundwater, a plumbing failure, surface runoff or a sewer problem? The cause matters to the investigation and to the insurance conversation.
A hypothetical property comparison
Imagine comparing two Queens houses. One has an attractive renovated lower level but no clear repair records. By comparison, the other has an older finish with documented drainage work and an inspection report identifying remaining questions. Choose neither solely for its finish quality.
The better next step is to obtain comparable evidence for both properties. Ask what can be verified, what remains uncertain and what further review would cost. This is a decision-making example, not a report about real homes currently offered by Aida.
Give your inspector a focused brief
Before the inspection, explain the water-related questions that came from the records and maps. Ask the inspector to describe the scope of the inspection, accessible areas and any limitations. If the inspector recommends a specialist, establish which question that person should answer.
- Do accessible areas show signs of past or current moisture?
- How do exterior grading and accessible drainage features appear?
- Can the inspector assess lower-level openings and entrances?
- Where does the building house important mechanical and electrical systems?
- Which conditions require further assessment?
- Did access or weather prevent any part of the inspection?
Do not expect a general inspection to certify that a property will never experience flooding. Ask for clear findings and next steps within the professional’s scope. A dry inspection day cannot reproduce every storm condition.
Check flood insurance before finalizing the budget
The National Flood Insurance Program’s buyer guidance explains that most homeowners and renters policies do not cover flood damage. Building and contents coverage are typically separate, with their own deductibles. NFIP coverage also has important exclusions and limitations, including for basement belongings and temporary living expenses.
Have an insurance professional evaluate the exact address, building type and intended use. Obtain written explanations of the policy options, effective dates, deductibles and exclusions. Do not assume a neighbor’s premium or a seller’s current arrangement will be your own.
Confirm any lender requirements separately. The fact that a lender does not require a particular policy does not settle the question of whether you want the protection. Likewise, the availability of insurance does not replace an inspection or make repair risk disappear.
Questions for condo and co-op purchasers
Discuss how the building’s insurance interacts with the coverage you would obtain personally. Your attorney and insurance adviser can explain the relevant documents. Instead of relying on a general assurance about insurance, identify possible deductibles, uncovered items and assessment exposure.
Also ask the managing agent about known building work and relevant reserves. Repairing a common system can affect shareholders or unit owners through the building’s finances. Our Queens condo and co-op comparison explains why ownership structure matters in these conversations.
Separate mitigation ideas from approved work
It may be sensible to investigate drainage changes, equipment relocation or other improvements. Have an appropriate professional assess feasibility, approvals and cost before treating any measure as a solution. What works at one property may be unsuitable at another.
Request an itemized scope and ask what the work is intended to address. A proposal should make the limits clear. Do not treat a small repair allowance as proof that a major drainage or flood issue can be resolved within that amount.
For a co-op or condo, check building approvals before assuming you can alter windows, mechanical equipment or common elements. For a house, ask about any applicable permits and property constraints. A buyer’s plan should match the work that can actually be approved and completed.
Build a purchase decision file
Organize the information into four groups: public screening results, seller or building records, professional findings and insurance terms. Add a short list of outstanding questions. Assign each question to the person qualified to answer it.
Then consider the financial consequences. Which immediate repairs did the professionals identify? How much would ongoing insurance cost? Decide what reserve would make you comfortable. Finally, list the uncertainties that remain unresolved. These questions connect the investigation to your actual budget.
Aida’s Astoria and Queens buyer service can help coordinate the property search and the questions to raise. Technical, legal and insurance conclusions should come from the appropriate professionals.
Frequently asked questions about Queens flood risk
Does an inland Queens location mean there is no flood risk?
No. Investigate rainfall and drainage questions as well as coastal exposure. Use the exact address and property records rather than making a borough-wide or neighborhood-wide assumption.
Can a flood map tell me whether a basement is legal living space?
No. Flood screening and legal occupancy are separate checks. Ask your attorney and an appropriate building professional to review the occupancy records and any relevant approvals.
Is an upper-floor condo unaffected by building flooding?
Review common equipment, access, insurance and building finances as well as the apartment. Unit elevation alone does not answer those questions.
Should flood risk automatically rule out a property?
A purchase decision depends on the evidence, professional advice, cost and your tolerance for uncertainty. Avoid automatic conclusions from a single screenshot. Contact Aida Home Realty to discuss your Queens search and organize the next steps.
Official resources checked October 28, 2026. Maps are screening tools, and this article does not determine flood exposure, insurance coverage or engineering suitability for a particular property.